There is no doubt that technology has made transacting business in Nigeria effortless but in a twist of irony it has also fueled a surge in fraud in form
There is no doubt that technology has made transacting business in Nigeria effortless but in a twist of irony it has also fueled a surge in fraud in form of fraudulent SMS alerts targeting unsuspecting citizens thus driving financial insecurity, reportsThe text message arrived seamlessly, albeit mimicking the legitimate government notifications which left no suspicion whatsoever.
While warning motorists of a sudden traffic violation, it thus elicited a sharp sense of urgency and directed recipients to a portal where the alleged offence could be reviewed and settled. For motorists routinely managing their public services online, there was little reason to suspect a trap. But the embedded link did not belong toThe distressing experience of Nollywood artist Adekanla Desalu underscores this dangerous new trend of financial ruin delivered via text alerts.
Desalu recounted his shock at discovering that $2,500 had vanished from his account after he responded to an SMS masquerading as an official FRSC notice—even though the prompt had only specified a modest ₦2,500 fine. Narrating his ordeal, Desalu admitted he lowered his guard because the format closely mirrored genuine traffic citations he had dealt with in the past.
“Yesterday, I got that message while I was in the middle of trying to get to work,” he explained. “I saw a link saying I beat the speed limit. Unfortunately, I clicked on it. ” The fraudulent portal requested his details to process the ₦2,500 penalty.
“I put in my information and made the payment, thinking it was a progressive digital system. I even told a colleague in the office, who mentioned that the authorities had been deploying these digital tickets for a while, making me feel quite proud of the system. Sadly, it was a trap. ” What makes Desalu’s story particularly cautionary is his professional background.
“I am usually incredibly meticulous about security because I worked within the banking industry for many years. I understand fraud patterns, but I completely missed this one. By the time I got home, I realized they had debited me $2,500. I blocked my cards immediately and filed reports, but the funds were already gone.
” Lamenting his loss on social media, he wrote: “From ₦2,500 to $2,500, God abeg. Please DO NOT click on any links you get via SMS or email without double or triple-checking that it is LEGIT. You can’t be too careful. ” Tagging official handles like @frscnigeria and @ekolastma_, he added, “Help us with authentic message titles and tips to avoid falling prey.
I’m so sad. ” Desalu is far from alone. Popular actress Peggy Ovire echoed the alarm, revealing a similar blow to her own family: “They just did my Dad dirty too; they took a whole ₦2 million from his account. ” Conversely, some motorists escaped financial disaster by sheer circumstance.
Kenneth Joseph related to The Nation how a brief logistical distraction saved him from the trap.
“I clicked the link when the message arrived,” Joseph shared. “But because I didn’t know my vehicle license plate number offhand and couldn’t go outside to check it, I minimized the browser tab. Shortly after, I saw someone online warning about the exact same scam tactic, so I rushed back and deleted the text immediately. ” These compounding accounts vividly expose the underbelly of Nigeria’s evolving financial ecosystem.
The trend has reignited deep anxieties regarding the vulnerabilities of the country’s rapid pivot to digital payments and digitized public utilities. These concerns are amplified as the nation approaches the high-velocity “ember months”—a season traditionally defined by surging consumer spending, peak travel, and hyperactive transaction volumes. This particular wave of attacks, which gained traction in September, relies heavily on texts spoofing the FRSC. Typical variations include: “FRSC: You have a new road traffic offence record that requires handling.
Please review the relevant details,” or “FRSC: your vehicle has a recorded speed limit violation. Please review and settle the offence. ” A third iteration warns: “An electronic traffic violation ticket has been issued for your vehicle; please handle, check, and pay it promptly. ” Each message is anchored by a link to a fraudulent gateway.
The Corps has since completely disowned the messages, explicitly flagging frscgov.top/ng as a known malicious URL and emphasizing that the agency maintains zero ties to it. For many citizens, however, the official disclaimer arrived long after the damage had been done. In another instance, the financial fallout was triggered by a fake ₦5,000 fine. An Instagram creator known as mcmonicacfrn documented losing nearly ₦2 million within 12 hours of interacting with the phishing link.
“I don’t even know who to hold accountable—whether it’s my telecommunications provider or the road safety agency,” he stated, visibly shaken. “I received an SMS about a traffic violation, clicked the link, and paid a minor fine of ₦5,000. By the time I woke up the following morning, my entire balance was wiped clean. My account officer told me nothing could be done to recover it.
I am still completely numb and confused. FRSC, how did our data get into the hands of these syndicates? ” Amid the rising casualties, a segment of the motoring public has managed to evade the trap through heightened skepticism. For these individuals, a deliberate look at minor anomalies was enough to prevent catastrophe.
A motorist named Gladys told The Nation that her suspicions flared when the payment page offered exclusively one option: direct card input. Having settled a legitimate traffic citation earlier in the year, she distinctively remembered that the genuine government portal accommodated three separate payment channels. The discrepancy served as an immediate red flag, prompting her to close the page. Similarly, gospel artist Neon Adejo identified the message as a fabrication instantly.
“I received the alert, and I knew right away it was fake. The text cited a violation in Abuja, but I have never driven a vehicle on any road in Abuja,” he remarked. For Jumoke Badmus, a roadside fruit vendor, the scam bordered on the absurd. She received the identical viral text message twice despite not owning a car.
“I laughed out loud when the texts landed because it was obvious it came from fraudsters. ‘Detty December’ is right around the corner, so these criminals are working overtime to secure their own holiday funds,” she observed. These varied outcomes, notes cybersecurity analyst Victor Okeh, demonstrate that basic attentiveness remains one of the most reliable shields against digital theft.
While Gladys leaned on her memory of past official protocols, Adejo and Badmus evaluated the context against their personal realities to spot the lies.
“But that is exactly where the risk resides,” Okeh explained to The Nation. “Fraudsters don’t need a flawless or completely bulletproof narrative. They only need to present a message that looks plausible enough to provoke a panicked, impulsive reaction before the victim can pause to think critically. ” “By mimicking the exact vocabulary, branding elements, and time-sensitive pressure of legitimate regulatory bodies, bad actors are transforming everyday text threads into digital minefields.
In this environment, a user’s deliberate caution stands as the absolute final barrier between an deceptive click and an entirely emptied bank account. ”According to Okeh, the latest FRSC scam succeeds by exploiting three specific psychological triggers: authority, urgency, and convenience. The illusion of authority is established by co-opting the trusted name and identity of the Federal Road Safety Corps. Urgency is manufactured through the alarming claim that a traffic violation has occurred and demands immediate action.
Finally, convenience is offered via an embedded link promising an instant resolution. This specific combination, Okeh notes, forms the foundational blueprint of successful phishing attacks. As the fraudulent text messages spread across the country, the Federal Road Safety Corps moved swiftly to distance itself from the campaign, utilising its official public platforms to warn motorists. The Corps explained that the texts are explicitly designed to induce panic by falsely informing recipients of a newly recorded traffic violation.
Victims are then manipulated into clicking an embedded link under the guise of reviewing their case details. The agency strongly cautioned that interacting with these links routes users to counterfeit clone portals engineered to harvest personal, financial, and authentication data. The FRSC specifically flagged the URL frscgov.top/ng as a known fraudulent domain in circulation, emphasising that it has absolutely no affiliation with the agency.
To prevent further victimisation, the Corps reiterated that its legitimate web footprint is exclusively hosted at frsc.gov.ng, and all official digital services are anchored within verified, authorised state infrastructure. Motorists are urged to treat any notification directing them to outside, unauthorised portals as completely fraudulent. In a bid to stem the tide of financial loss, the FRSC has issued strict directives to the public.
Citizens who receive these messages are advised to ignore the prompts, refrain from clicking any embedded links, and never authorise payments. The agency warned against transmitting bank account numbers, security passwords, credit card credentials, driver’s licenses, or vehicle registration details through unsolicited electronic channels. Instead, the Corps advises motorists to verify any alleged road infractions directly through verified channels.
Rather than trusting incoming texts, drivers can cross-check their records directly on the official portal or call the national toll-free emergency line 122. Individuals who have already received the fraudulent messages are urged to preserve the text as evidence, cease all interaction with the sender, and report the occurrence to the appropriate regulatory bodies.
Amplifying these security concerns, the Nigeria Data Protection Commission has issued a stern advisory warning citizens against acting on any electronic communication that lacks independent verification. In its general data protection memo, the Commission noted that cybercriminals are increasingly weaponising fear, high-pressure deadlines, and the appearance of institutional authority across various digital channels—including simulated traffic rule violations. These tactics are carefully tuned to bully unsuspecting targets into clicking malicious links, downloading malware, or complying with harmful financial demands.
The NDPC has urged Nigerians to rigorously scrutinise incoming sender details, root domain names, and hyperlinks before taking action. If the legitimacy of a text message is even slightly in doubt, users should completely disengage and independently contact the relevant institution using a known, verified telephone number, official portal, or public corporate email address.
Furthermore, the public is encouraged to flag suspicious communications and identity theft attempts directly to both the commission and the impersonated agency. Beyond basic awareness, the NDPC recommends robust digital hygiene, such as deploying strong, unique passwords across platforms and activating multi-factor authentication wherever supported. Anyone who suspects an account breach should rotate their passwords immediately. The Commission’s ultimate takeaway is simple: the mere appearance of official backing should never trigger immediate compliance.
Under its core directive—”STOP. VERIFY. PROTECT. REPORT.
”—the agency reminds Nigerians to never let synthetic urgency override standard caution. Ultimately, the NDPC stresses that data protection is a collective responsibility, and any electronic message that cannot be independently validated must be entirely disregarded. The FRSC is not the only Nigerian institution to have been impersonated through digital channels. In late 2025, the Ibadan Electricity Distribution Company warned customers about fraudulent SMS messages claiming that recipients were entitled to electricity-bill refunds.
The messages directed recipients to a third-party website which the company identified as a phishing site and warned customers not to provide banking details, card information, BVN, OTPs, passwords or other personal information. The scam has changed with technology, but its basic psychology has remained remarkably consistent: make the message appear trustworthy, create urgency and persuade the recipient to act before thinking twice. The story goes back to the early years of GSM in Nigeria.
When mobile telecommunications expanded rapidly in 2001, millions of Nigerians suddenly became reachable through text messages. Fraudsters quickly saw the opportunity. Early scams often came in the form of supposed telecom lottery promotions. Recipients were told they had won large sums of money and were asked to provide recharge-card PINs to claim their prizes.
Once the PINs were sent, the promised winnings never came. Between 2012 and 2015, around the period when the Central Bank of Nigeria’s Cashless Policy was encouraging Nigerians to adopt electronic payments, fraudsters increasingly used SMS to target bank customers. Messages warned recipients that their accounts or ATM cards had been blocked because of issues such as Bank Verification Number requirements or regulatory checks.
Some victims were directed to fake customer-care numbers where criminals attempted to obtain confidential banking information. By the middle of the decade, the financial consequences were becoming more visible. The Nigerian Inter-Bank Settlement System recorded more than N3 billion in annual losses to banking fraud between 2014 and 2017.
Among the schemes were fake requests for confidential banking information and the emerging “fake bank alert”, in which criminals fabricated transaction notifications to convince traders and Point-of-Sale operators that payments had been made. A 2015 study also found that all mobile subscribers surveyed in Nigeria had received spam SMS, with respondents receiving an average of 2.45 unsolicited messages a day. As mobile banking and electronic payments became part of everyday commerce, fraudsters continued to adapt.
Between 2016 and 2020, fake bank alerts became increasingly familiar. A fabricated transaction notification could convince a trader that money had been transferred, allowing a fraudster to collect goods or cash before the transaction was verified. From 2021 onwards, the deception became harder to distinguish from legitimate communication. Fraudsters increasingly mimicked banks’ sender identities and short codes, while malicious links were used to direct victims to imitation banking websites designed to capture credentials and other sensitive information.
SIM-swap fraud and other forms of identity compromise added another layer to the threat. By 2025 and into the present, the impersonation had expanded beyond banks. Government agencies, electricity companies and other trusted institutions became potential identities for scammers to exploit. The latest FRSC messages are a continuation of that evolution: the old SMS scam adapted to a new digital environment.
The growing sophistication of such schemes is occurring against the background of Nigeria’s rapid digitalisation of financial services. Electronic payments have become integral to commerce, banking, government services and everyday transactions. The Central Bank of Nigeria’s Payments System Vision 2028 explicitly places security, trust, collaboration, inclusion, innovation and interoperability among the guiding principles of the country’s payment-system strategy.
The CBN has said the payment system is fundamental to the economy because it provides the channels through which financial resources move between different segments of the economy. Its payments-system framework has consequently placed emphasis on safety, reliability, resilience, consumer protection and stronger authentication. Data contained in the apex bank’s 2028 document showed that attempted fraud across the country’s banking and payments ecosystem reached about N187.79 billion between 2020 and 2025. Of this, N134.48 billion was actually lost.
The losses occurred across internet and mobile banking, cards, Point-of-Sale terminals and other electronic payment channels, bringing the problem closer to the everyday financial lives of Nigerians. Actual losses rose gradually from N11.61 billion in 2020 to N12.77 billion in 2021, N14.32 billion in 2022 and N17.67 billion in 2023.
Then came a sharp jump in 2024, when losses soared to N52.26 billion — the highest recorded in the period. The 2024 figure alone represented nearly 39 per cent of the total N134.48 billion lost over the six years. The CBN attributed much of the increase to a major internal fraud case involving N30 billion.
Attempted fraud followed a similar pattern, increasing from N13.26 billion in 2020 to N14.48 billion in 2021, N16.41 billion in 2022 and N19.72 billion in 2023 before rising dramatically to N86.36 billion in 2024. The figures fell in 2025, with attempted fraud declining to N37.57 billion and actual losses to N25.85 billion. But behind these statistics are real people, real accounts and, in many cases, hard-earned money lost through a single moment of trust.
For some victims, that moment begins with an ordinary-looking text message. It may warn of a traffic offence, demand payment of a fine or direct the recipient to a website that appears legitimate. What follows can turn a seemingly harmless SMS into a costly encounter with fraud. Okeh, highlighting the latest FRSC incident, said it is particularly instructive because the initial point of contact was not a financial institution.
It was a road-safety agency. The fraudsters therefore exploited institutional credibility before attempting to reach financial information. The same tactic, he said, can be applied to electricity companies, telecommunications operators, government agencies, delivery companies, tax authorities, schools and other organisations whose names consumers recognise.
“The wider implication is that cyber security can no longer be treated exclusively as a banking-sector issue. For businesses, a compromised brand can translate into financial losses, reputational damage, customer distrust and additional compliance costs.
“For government agencies, the stakes are equally significant because digital platforms are increasingly being used to deliver public services. A fraudulent website impersonating a public institution does more than steal money. It can undermine confidence in the institution’s legitimate digital infrastructure,” Okeh stated.
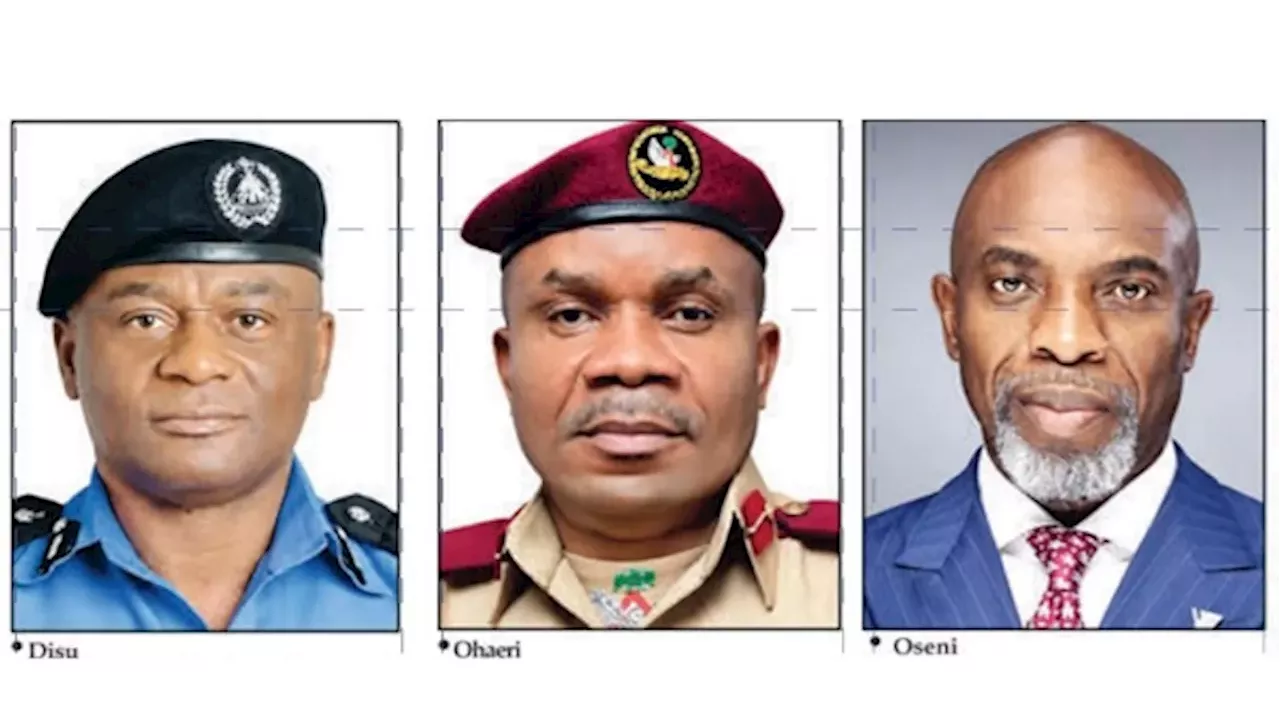
Against this backdrop, the Nigeria Police Force has begun strengthening the channels through which members of the public can report cases of financial fraud, as the growing use of digital platforms creates new avenues for scammers to target unsuspecting victims. On September 1, 2026, Inspector-General of Police Olatunji Disu launched the NPF Vigilant App and the NPF-MTN Closed User Group Network.
The Vigilant App is designed to allow members of the public to report suspected fraud, upload evidence, track cases and receive feedback without necessarily having to begin the process by physically visiting a police station. The system also provides an administrative platform through which bank fraud desks and police personnel can communicate when investigations require law-enforcement intervention.
During a presentation at the Association of Chief Audit Executives of Banks in Nigeria’s 65th Quarterly General Meeting , Winner Martins, representing the NPF, explained that the platform was designed around collaboration between three principal groups, including customers reporting suspected fraud, financial institutions investigating complaints and the police handling enforcement. The initiative is significant because speed is often critical in financial fraud cases. A delayed report can make tracing, freezing or recovering funds more difficult.
The police platform is also intended to facilitate digital court-order processes, potentially reducing some of the delays associated with fraud investigations. For banks and other financial institutions, however, the challenge goes beyond recovering money after a fraudulent transaction. The sector increasingly has to protect customers against threats that begin outside the banking environment but can ultimately expose their accounts and financial information.
Wema Bank Managing Director/Chief Executive Officer, Moruf Oseni, recently warned that the rapid growth of artificial intelligence, digital platforms and automation was creating new dimensions of risk. He identified emerging threats including AI-enabled fraud, deepfakes, identity manipulation, cyberattacks, data breaches and business email compromise, highlighting how the fraud landscape is evolving alongside the technology used in everyday financial transactions.
Speaking while hosting ACAEBIN’s quarterly meeting, Oseni said: “Every transformation brings new dimensions of risk: AI-enabled fraud, deep fakes, identity manipulation, cyberattacks, API vulnerabilities, data breaches and business email compromise are no longer distant possibilities; they are increasingly tangible risks that demand the attention of boards, management, regulators and assurance functions alike. Technology may change the way we bank, but trust remains the currency upon which banking is built.
” His warning, Okeh said, captures the central business challenge created by the latest SMS scams. Financial institutions may strengthen their internal systems, but customers can still be attacked through a text message, social-media account or fake website outside the bank’s direct infrastructure. According to him, “That makes fraud prevention an ecosystem problem. ”The challenge is also forcing a rethink of the traditional role of internal audit.
Deloitte Nigeria Senior Manager, IT & Control Assurance, Chisom Odobeatu, told stakeholders and participants at the ACAEBIN meeting that internal auditors needed to move beyond retrospective reviews and develop capabilities to identify emerging technology risks before they crystallise. She said banks adopting AI needed more than policies. They needed inventories of AI systems, clear accountability, reliable data, appropriate controls, continuous monitoring and human oversight. The same principle applies to digital fraud.
Rather than waiting until customers lose money, financial institutions and other organisations increasingly need systems capable of identifying suspicious patterns and warning users before they act. Odobeatu also stressed the importance of cyber resilience, not merely preventing attacks but ensuring that institutions can withstand, respond to and recover from them. For banks that increasingly depend on cloud providers, fintechs and other technology partners, he said assurance must extend beyond the organisation’s own systems.
That becomes particularly important in an environment where the customer’s first interaction with a scam may take place on a platform controlled by neither the bank nor the government institution being impersonated. The timing of the FRSC scam is notable, coming as the ember months bring increased travel, shopping and financial activity. But SMS fraud is not a seasonal problem.
The current traffic-offence messages may fade from circulation, yet the tactic can easily be repurposed for electricity refunds, bank verification, parcel deliveries, tax demands or other official-looking notices. What changes is the story used to lure victims; the underlying strategy remains the same: exploit trust, create urgency and persuade people to act before verifying the message. The consequences extend beyond the money lost by individual victims.
Nigeria’s growing digital economy depends on people trusting electronic transfers, banking applications, online payments and government platforms. When that trust is undermined, businesses face higher verification and fraud-related costs, while consumers may become reluctant to use digital services. The CBN’s 2028 recognises trust and security as essential to a functioning digital payments ecosystem. The challenge, therefore, is not to slow digitalisation, but to ensure that security keeps pace with convenience.
Public awareness remains equally important. The FRSC and other institutions have urged Nigerians to verify unsolicited messages, avoid suspicious links and report suspected fraud. The principle is simple: when a message demands immediate action, pause and verify before clicking. The latest scam also shows why tackling digital fraud cannot be left to banks alone.
Financial institutions need stronger fraud detection, customer alerts and authentication systems, while government agencies must protect their digital identities and quickly expose fraudulent platforms. Telecommunications operators have a role in detecting and suppressing malicious messages, while law-enforcement agencies need faster channels for receiving reports and acting on them. Consumers, meanwhile, must recognise that an official-looking SMS is not proof of authenticity.
The police’s Vigilant App, the CBN’s payments-security framework and warnings from agencies such as the FRSC reflect a growing need for stronger coordination across the digital ecosystem. Ultimately, Nigeria’s digital transformation is here to stay. Nigerians can now transfer money, pay bills, access government services and conduct business without leaving their homes or offices. But every new digital convenience creates another opportunity for criminals to exploit trust.
The FRSC scam is therefore more than a warning about one fake website. It is a reminder that a message demanding a relatively small payment can become the gateway to a much larger loss. For some victims, the difference between safety and financial loss came down to a few seconds — whether to click or pause, trust or verify.
As digital transactions continue to grow, the real test will be whether the systems protecting that convenience can evolve quickly enough to keep pace with those seeking to exploit it. Abuja doctor reveals a unique way to permanently cure weak erection, small and shameful manhood, and infertility issues without side effects within a short period. Click now to see!!
EXPOSED AT LAST: Lagos Based Doctor Uncovers The Hidden Secret Mystery, To Enhance Your Small Penis Size, Cure Your Weak Erection, Treat Your Premature Ejaculation, Reverse Your Low Libido And Boost Your Bedroom Performance. Click Here Now To Discover This Top Secret That in Will Improve Your Sexual Health Today. NEWS UPDATE: Nigerians can now earn as much as $15,000- $25,000 with premium domains. You decide if you want payment in Naira or US Dollars.
Be sure to ask for evidence and proof of people benefitting daily from this. CLICK HERE TO START.
We have summarized this news so that you can read it quickly. If you are interested in the news, you can read the full text here.
Get an alert when there is news on Nigeria News
The Central Bank of Nigeria (CBN) has ordered companies issuing foreign-currency stablecoins in Nigeria to hold at least ₦15 billion in paid-up capital, the
Head Topics, publish breaking news of all around the world. Local headlines and stories are HeadTopics.com immediately.
SMS: How digital convenience became albatross to businesses – Head Topics